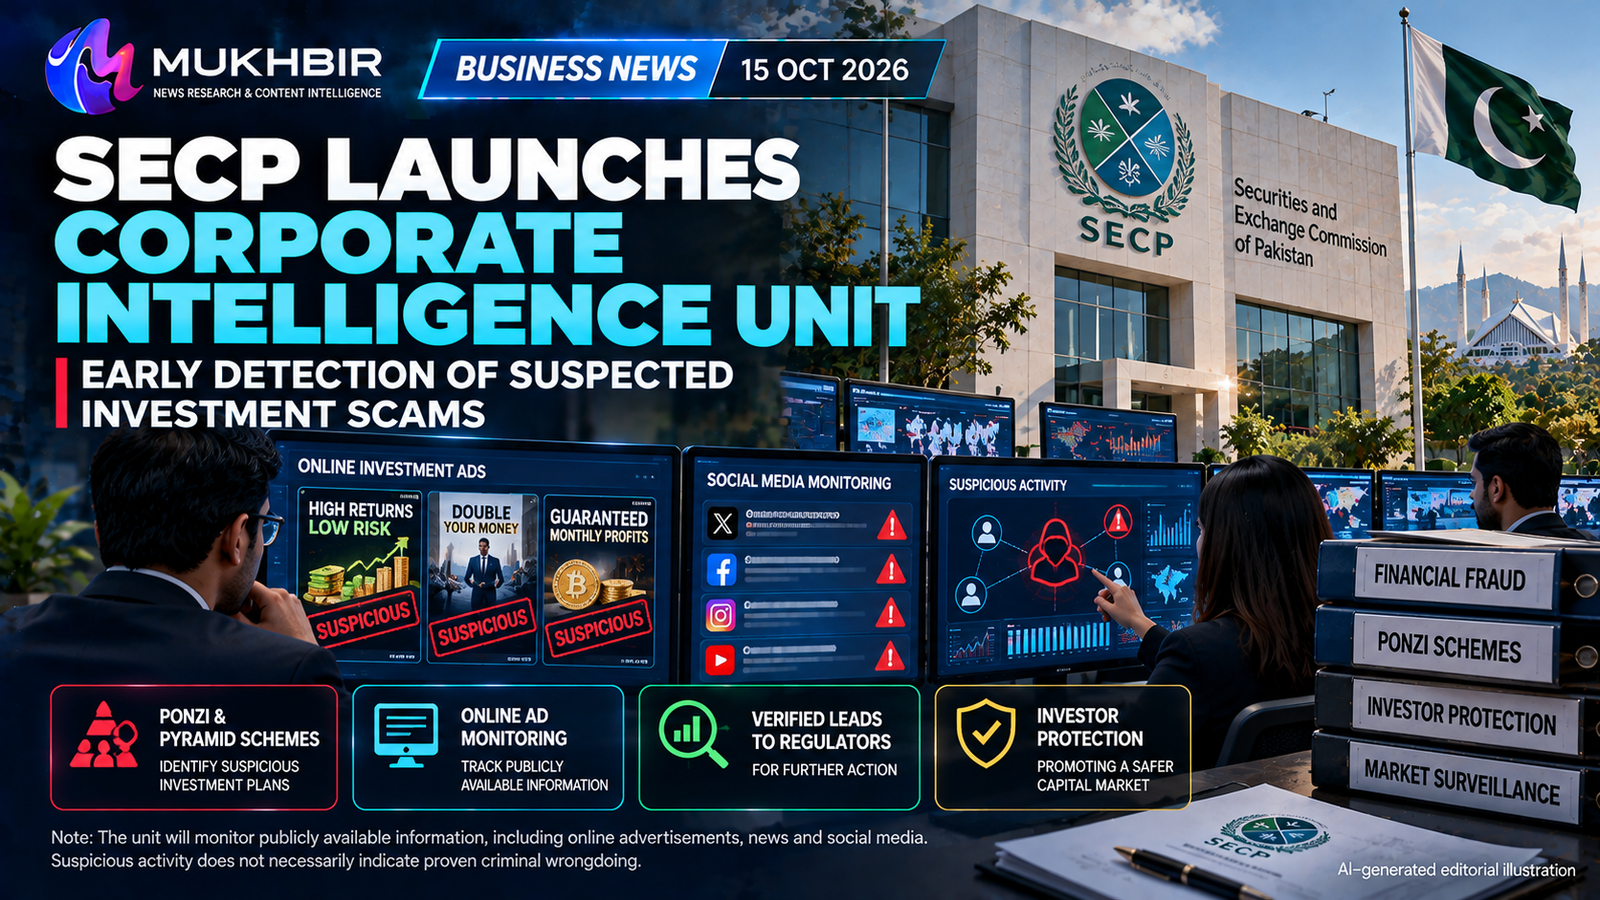
ISLAMABAD, October 15, 2026 — Pakistan’s Securities and Exchange Commission (SECP) has approved a new Corporate Intelligence Unit (CIU) designed to identify potentially illegal investment and financing activity before complaints reach regulators. Announced on October 14 and covered in the October 15 editions of Dawn and Business Recorder, the initiative will examine publicly available online information for warning signs of suspected misconduct.
The SECP Corporate Intelligence Unit 2026 will focus on registered companies suspected of operating Ponzi or pyramid schemes, accepting deposits or extending loans without the necessary authorisation, or carrying on businesses outside their approved objectives. Verified leads will be referred to relevant SECP departments for further examination and, where warranted, enforcement.
The announcement does not mean every company flagged in an online advertisement has committed an offence. It establishes an early-detection and referral function, not a finding of guilt or a guarantee that fraudulent activity will be eliminated.
What Has SECP Announced?
In its October 14 official statement, SECP said it had approved establishing a Corporate Intelligence Unit within the Chairman’s Secretariat. Its stated objective is to identify potential regulatory violations proactively, including before a formal complaint is received from the public.
The unit is being established under Section 20 of the SECP Act, 1997. Business Recorder reported that it will be headed by a director or additional director and supported by two officers.
The CIU is expected to monitor recurring patterns across public reports and advertisements, examine whether information merits further checking, and route credible concerns to the SECP team responsible for the relevant sector.
This is different from a police investigation or judicial proceeding. Its intelligence-gathering work can support those processes where legally appropriate, but a lead must be verified and handled by the competent authority.
Corporate Intelligence Unit 2026: Key Facts
Announcement date: October 14, 2026.
News coverage: Dawn and Business Recorder, October 15, 2026.
Regulator: Securities and Exchange Commission of Pakistan.
Unit: Corporate Intelligence Unit (CIU).
Legal basis: Section 20 of the SECP Act, 1997.
Organisational location: Chairman’s Secretariat.
Reported structure: Director or additional director, supported by two officers.
Main focus: Suspected Ponzi or pyramid schemes, unauthorised deposit-taking, unlicensed lending, and activities outside corporate objectives.
Main information channels: Public news, social-media posts and digital advertising.
No total of confirmed scams stopped, money recovered or prosecutions completed was announced as a result of the new unit’s creation.
What Is a Ponzi Scheme?
A Ponzi scheme is generally an arrangement in which earlier investors are paid using money from newer participants rather than proceeds generated from sufficient legitimate business activity.
Such schemes can temporarily appear successful because some people receive payments at first. Those payments may be used to persuade more people to participate, making the structure increasingly dependent on continued inflows.
A pyramid scheme typically relies heavily on recruiting additional participants, sometimes with commissions or rewards linked to the number of people recruited. Some illegal schemes contain characteristics of both.
These explanations describe common fraud patterns, not an assessment of any particular company. Whether a business has violated Pakistani law requires evidence and application of the relevant legal provisions.
Why Online Investment Advertising Is a Priority
Investment opportunities can spread quickly through short videos, messaging services, social-media pages and digital advertisements. Consumers may encounter attractive return claims without knowing who runs the business or whether it holds regulatory authorisation.
SECP’s initiative seeks to use publicly accessible material as an early signal that a business warrants closer attention. A pattern of repeated promotional claims, changing contact details or suspicious business descriptions could trigger verification.
A post advertising strong returns is not automatically proof of fraud. Conversely, polished design, public testimonials and large follower counts do not prove that an investment programme is lawful.
The value of intelligence monitoring depends on checking leads carefully and reducing the chance of wrongly targeting legitimate businesses.
What Does ‘Publicly Available Information’ Mean?
Dawn and Business Recorder say the CIU will monitor news reports, social media and digital advertisements. These are sources that can be assessed without treating private conversations as automatically accessible to a regulator.
The SECP announcement does not establish blanket access to private WhatsApp messages, personal bank accounts or encrypted correspondence. Any additional investigative access would require separate legal authority and applicable safeguards.
Using open-source information allows regulators to notice widely promoted activities that might not yet have generated formal complaints. Information from different public sources can help determine which claims need closer examination.
The specific software, databases and operating procedures of the new unit were not detailed publicly in the reporting reviewed.
Why Unlicensed Deposit-Taking Matters
Accepting money from the public as deposits or offering certain financial services can require authorisation under applicable law. A company’s incorporation or registration with SECP is not a substitute for a licence to perform every regulated activity.
A registered company can have a legitimate business purpose while lacking permission to offer a particular investment, lending or deposit product. That distinction is important when consumers see certificates of incorporation used in advertising.
SECP’s stated remit for the CIU includes identifying companies suspected of taking deposits or lending without the required licence.
The regulator has not named every such business in the announcement. Readers should not infer wrongdoing by specific companies solely from the creation of the monitoring unit.
How Will Suspicious Leads Be Handled?
The proposed workflow begins with identifying signals from publicly available material. Those signals are then checked to determine whether they appear credible and relevant to the SECP’s powers.
According to the official statement, verified leads will be referred to appropriate SECP departments for inquiry or enforcement action. The division receiving a referral would determine next steps using its established procedures.
Where appropriate, information may also be shared with other government institutions, including the Federal Investigation Agency, National Cyber Crime Investigation Agency, State Bank of Pakistan and National Accountability Bureau.
Referral does not necessarily result in a criminal case, arrest, penalty or conviction. Every stage has its own legal and evidentiary requirements.
Coordination With FIA, NCCIA, SBP and NAB
Financial wrongdoing may overlap with cybercrime, banking regulation, corporate law and other matters. A public investment advertisement could, for example, relate to a registered company, a digital platform or a payment arrangement.
SECP said the CIU could share relevant leads with the FIA, NCCIA, SBP and NAB where appropriate. The announcement signals potential interagency coordination rather than an automatic transfer of every flagged case.
The State Bank of Pakistan has separate responsibilities concerning regulated banks and payments, while other authorities act under their own legal frameworks.
Cooperation could help avoid gaps between institutional mandates, but the announcement does not provide statistics proving that interagency enforcement outcomes have already improved.
Why Early Detection Could Help Investors
Some investors approach authorities only after promised payments stop or a promoter becomes unreachable. By that point, recovering funds can be difficult and further individuals may already have transferred money.
A monitoring function that identifies warning signs sooner could support timely public warnings, regulatory scrutiny and referrals. SECP has presented this as part of its risk-based surveillance approach.
Earlier detection is a potential benefit, not a guaranteed result. Success will depend on verification quality, staffing, coordination, enforcement capacity and public awareness.
Measures such as the number of actionable leads, warnings issued and completed cases could eventually help assess performance if SECP publishes comparable figures.
What SECP Chairman Said About the Unit
Business Recorder identified SECP Chairman Dr Kabir Ahmed Sidhu as saying that the new capability would strengthen risk-based surveillance by transforming open-source information into verified regulatory leads.
The regulator’s emphasis is on identifying emerging risks before they lead to greater investor losses. That represents a shift toward proactive monitoring alongside conventional complaint-driven action.
It remains necessary to distinguish a policy objective from an achieved result. The unit’s effect on illegal schemes can only be assessed after operational experience and reported outcomes.
No definitive national estimate of annual investor losses prevented by the CIU has been established in these announcements.
What Does This Mean for Legitimate Businesses?
Registered businesses promoting financial products may face closer attention to how their services are described, what permissions they hold and whether advertising accurately reflects their activities.
The creation of a surveillance unit does not itself change every corporate registration requirement or introduce a new universal financial licence. Companies must continue to follow the laws already applicable to their particular activities.
Transparent disclosures and consistent business descriptions can make it easier for consumers to understand products and for regulators to distinguish legitimate activity from misleading promotion.
A compliance check should not be confused with an accusation. Businesses are entitled to proper process and the ability to address concerns according to applicable rules.
The Difference Between Company Registration and Investment Approval
A crucial warning for consumers is that registration as a company does not automatically certify a business as a safe investment provider.
A promoter may display a registration number, website or office address. Those details may show that a corporate entity exists, but they do not independently establish authorisation to take deposits, manage investments or provide regulated lending.
Before investing, consumers should verify the service being offered and whether a relevant licence is required and held. They should use the regulator’s official resources rather than trusting screenshots forwarded by an unknown promoter.
No investment is made risk-free merely because a company is properly licensed. Legitimate investments can still lose value.
How Can People Spot Warning Signs?
Promises of unusually high fixed returns with little or no risk deserve particular scrutiny. An investment that depends on recruiting new members may also warrant questions about where its revenues actually originate.
Other reasons to pause include pressure to transfer funds immediately, confusing ownership details, inconsistent documentation and difficulties receiving clear explanations of the business model.
These signals are reasons to investigate rather than definitive proof that a named business is committing fraud.
Consumers should preserve receipts, contracts and communications when raising concerns. They should avoid sharing passwords, banking access codes or unnecessary identification documents with unofficial contacts.
Should Investors Report Suspicious Schemes?
People concerned about potentially unlawful investments can consult SECP’s official website for current investor information and complaint channels. The responsible authority may vary depending on the product or suspected conduct.
A useful report typically explains what was offered, who promoted it, how payments were requested and what documentation exists. Avoid publishing unverified personal allegations or sensitive records in open social-media comments.
Reporting a concern does not automatically entitle a person to reimbursement. Claims, enforcement and recovery depend on specific facts and legal processes.
The new CIU may help regulators discover risks without waiting for formal complaints, but public reporting and consumer due diligence remain valuable.
How This Fits Into Pakistan’s Digital Economy
Pakistan’s digital commerce and investment ecosystem has expanded the number of ways people encounter financial products. Smartphones and online advertising can make services easier to discover, but also allow misleading promotions to reach large audiences quickly.
Regulatory surveillance of public digital information may become more significant as financial marketing moves across platforms and formats.
The wider business issue is trust. Investors, entrepreneurs and legitimate providers can benefit when financial claims are clearer and suspected unlawful activity is examined through fair procedures.
However, the CIU announcement does not prove a particular online platform has been banned, or that all digital investment advertisements must now be approved in advance.
Potential Impact on Capital Markets
Consumer confidence is important for formal capital markets and regulated investment services. Highly publicised fraud cases may discourage participation when people cannot distinguish legitimate products from misleading promotions.
Proactive intelligence can complement investor education and normal licensing oversight, although the precise effect on capital-market participation remains unknown.
The unit has not been presented as a programme to influence daily Pakistan Stock Exchange share prices or guarantee investor returns.
It is primarily a regulatory and investor-protection development, not a signal to buy or sell specific securities.
What Happens Next?
The next meaningful updates will concern operational procedures, any published guidance, referrals and enforcement outcomes attributable to the CIU.
SECP may also issue targeted warnings or cooperate with other authorities where evidence warrants action. Each development should be reported according to its official status.
It would be premature to claim that the establishment of the unit has already resulted in a specified number of arrests, recovered funds or closed schemes.
As of October 15, 2026, the verified development is SECP’s approval of a Corporate Intelligence Unit designed to turn publicly observable warning signs into checked regulatory leads.
Frequently Asked Questions
What is the SECP Corporate Intelligence Unit 2026?
It is a newly approved unit intended to proactively identify potentially illegal corporate investment and financing activities using public information.
When did SECP announce the unit?
SECP announced its approval on October 14, 2026; Dawn and Business Recorder covered it on October 15.
What kinds of schemes will it monitor?
Its stated focus includes suspected Ponzi and pyramid schemes, unlicensed deposit-taking and lending, and activities outside approved corporate objectives.
Will the CIU monitor private messages?
The announcement specifically refers to publicly available news, social media and digital advertisements. It does not establish unrestricted access to private messages.
Can the unit arrest people directly?
The reported plan concerns identifying and referring verified leads. Any investigative or coercive action must follow the authority and legal process of the responsible institution.
Which agencies could receive information?
SECP identified the FIA, NCCIA, SBP and NAB as potential coordination partners where appropriate.
Is every SECP-registered investment company approved?
No. Corporate registration does not automatically provide every licence needed to offer regulated financial services.
Does the new unit guarantee protection against scams?
No. It may improve early detection, but prevention, enforcement and recovery depend on evidence, resources and legal processes.
About The Author