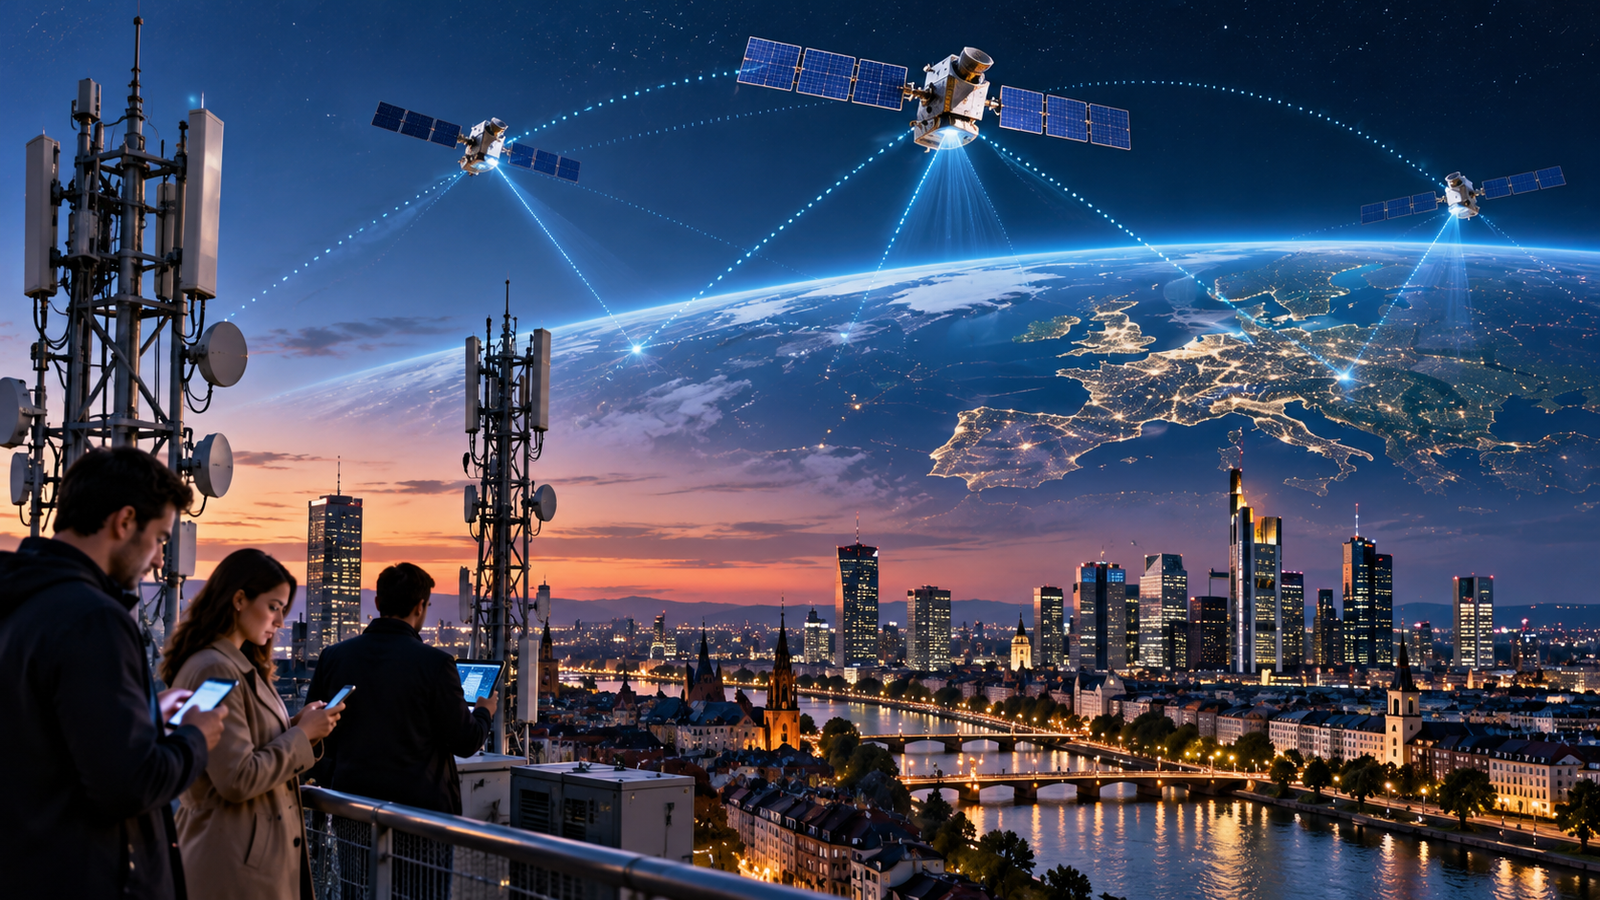
Four of Europe’s biggest telecommunications operators are exploring a joint bid for mobile satellite spectrum as they seek to expand direct-to-device connectivity and reduce reliance on overseas satellite networks. Deutsche Telekom, Orange, Telefónica and Vodafone signed a letter of intent to study cooperation, according to Reuters reporting published October 19 and further coverage on October 20, 2026. The initiative could eventually allow ordinary mobile phones to connect to satellite networks in locations beyond the reach of conventional cell towers.
The news is significant for competition with SpaceX’s Starlink, but the distinction between a plan and a service launch is essential. The four operators have not announced an operational European satellite mobile network, won spectrum rights or named a definitive satellite partner. Their immediate step is to consider a joint bid for spectrum linked to future mobile satellite services, subject to regulatory and commercial decisions.
What Have the Four Telecom Operators Announced?
The companies signed a letter of intent to explore a joint bid for mobile satellite service spectrum, Reuters reported. The participants are Germany’s Deutsche Telekom, France’s Orange, Spain’s Telefónica and UK-based Vodafone, all major network operators with customers and infrastructure in several European markets. The proposed cooperation would bring together expertise in terrestrial mobile networks and commercial relationships with millions of users.
A letter of intent signals an intention to investigate collaboration, rather than a final investment contract or guaranteed service. The precise ownership structure, allocation of costs, timing and operating arrangements have not been established in the reporting reviewed. Readers should therefore avoid headlines that claim the four companies have already launched a Starlink rival.
Why Is Europe Interested in Satellite-to-Phone Services?
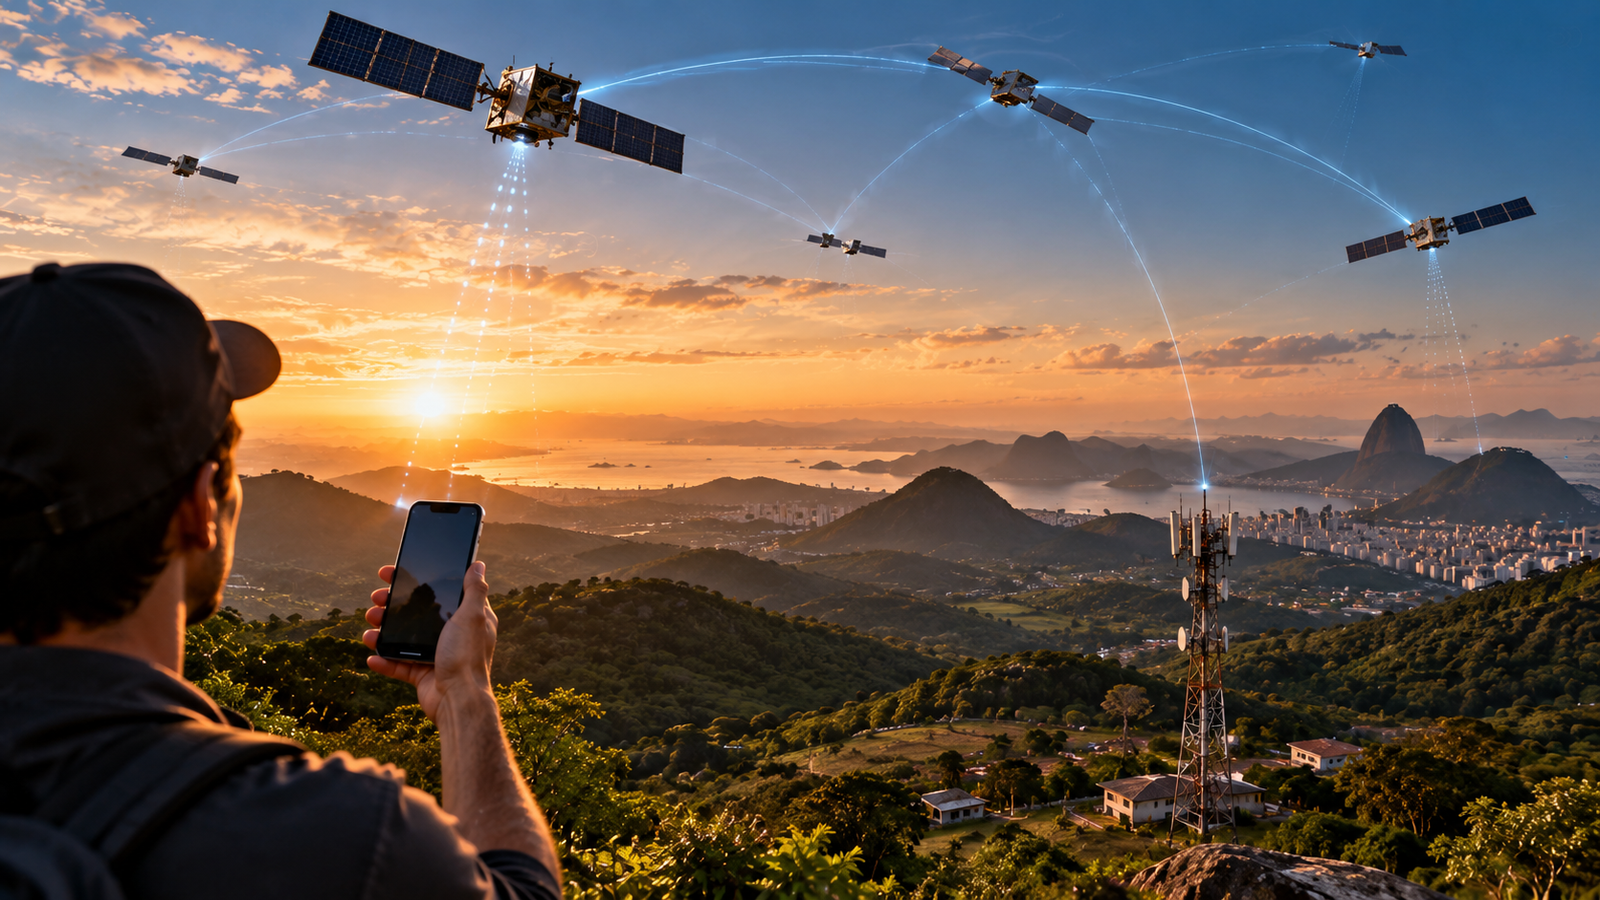
Mobile networks offer widespread coverage, but remote countryside, mountains, islands and transport corridors can still experience poor signal availability. Satellite-to-device technology aims to complement conventional towers by providing some level of connectivity directly to compatible phones. This may be particularly useful for emergency messaging, resilience during infrastructure failures and communications in sparsely populated locations.
There is also a strategic dimension. European policymakers have expressed interest in resilient communications systems that are not wholly dependent on providers outside Europe. The competitive debate extends beyond convenience for consumers to issues of spectrum allocation, national security, infrastructure control and the rules governing cross-border satellite services.
What Is Direct-to-Device Satellite Connectivity?
Direct-to-device, often shortened to D2D, refers to communication between a satellite and consumer equipment such as a smartphone. Some services support basic emergency messaging while more advanced systems aim to provide text, voice or data features. The exact experience depends on the satellite constellation, radio spectrum, handset hardware, software, geographic conditions and regulatory permissions.
This is not the same as standard home satellite broadband supplied through a dedicated rooftop or portable terminal. A satellite link to an ordinary phone faces tighter constraints on antenna size and available power. Consumers should not assume that a proposed satellite mobile service will immediately provide the same speeds, indoor coverage or capacity as a terrestrial 5G connection.
What Is the Role of Europe’s 2 GHz Spectrum?
Reporting by The Financial Times and The Verge said the proposed cooperation concerns mobile satellite service spectrum around the 2 GHz band. Access to these frequencies matters because spectrum rules determine who can operate radio services and under what conditions. The European Commission has been considering its approach to future allocations, making the regulatory process a central part of the business opportunity.
The band is not simply unused space that any company can occupy. It is subject to licensing, interference management and coordination requirements. The four operators’ potential bid would have to fit the applicable European process. Neither the frequency rights nor the service capabilities should be treated as secured before regulators make formal decisions.
Would the Operators Build Their Own Satellites?
The proposal is not understood to require the four telecom operators to build and launch an entirely new satellite constellation themselves. The Verge reported that they expect to manage or develop ground infrastructure and seek an external partner to supply the space segment. That model would combine existing operator knowledge of mobile customers and terrestrial networks with another provider’s orbital assets.
The identity of a future satellite partner has not been confirmed. European companies such as Eutelsat have been discussed in reporting as possible candidates, but a candidate is not a signed supplier. Launch capacity, satellite performance, coverage commitments and compatibility with mobile devices would all influence whether a partnership could be commercially practical.
How Does This Relate to Starlink?
SpaceX’s Starlink has become an important supplier of satellite internet and has been developing services that can connect directly with mobile devices through telecom partnerships. The European initiative is widely framed as a potential competitive response because it aims to give major regional carriers more influence over how satellite mobile access develops. Competition could broaden choices, encourage investment and place pressure on providers to improve coverage.
But there is not yet a functioning European product to compare head-to-head with Starlink Mobile. Starlink has already deployed substantial satellite infrastructure, while the four operators are evaluating a bid and possible network arrangements. Their relative cost, performance and availability cannot be established from a letter of intent. Any eventual comparison must be based on launched services and verified performance data.
Why Regulators Are Central to the Story
Satellite communications depend on licenses, spectrum coordination, market access and rules addressing public safety. In Europe, the future of the relevant satellite spectrum is under discussion, and decisions may affect established providers as well as new entrants. Reuters described the proposed consortium as an attempt to position European telecom operators for those forthcoming decisions.
Advocates of reserving spectrum for European operators may argue that it strengthens communications resilience and strategic autonomy. Critics may say restrictive allocations could reduce competition, limit consumer choice or complicate services offered by global providers. These are competing policy considerations, not evidence that any particular option has been adopted. The ultimate outcome will depend on regulatory decisions and their implementation.
What Could This Mean for Mobile Customers?
For customers, the most visible long-term opportunity is better basic connectivity where mobile towers cannot provide a reliable signal. The technology could support emergency alerts, remote travel and resilience during power outages or local disasters. Integrated billing through existing mobile carriers might also make satellite features easier to access than buying separate hardware.
However, prices, supported countries, compatible phones, service speeds and launch dates have not been announced by the proposed four-operator arrangement. A user should not purchase a handset or change network provider on the assumption that a particular new satellite service is guaranteed. Real-world availability will require regulatory approval, infrastructure and commercial product launches.
Why the Ground Network Still Matters
Satellite systems do not eliminate the need for terrestrial infrastructure. They require connections to core networks, gateways, network-management platforms and customer-service systems. Conventional towers remain important for dense urban coverage and high-capacity data use. The operators’ expertise in terrestrial networks could help integrate a future satellite service with existing mobile plans.
Such integration comes with engineering challenges involving roaming, authentication, radio interference, handovers and reliability. Satellite capacity is not unlimited, particularly when large numbers of users try to connect in the same area. The technology should therefore be presented as a complement to conventional networks rather than an immediate replacement for fibre broadband or 5G towers.
What Are the Commercial and Investment Challenges?
A European direct-to-device service would require spending on equipment, integration, spectrum rights and customer support. It would also depend on finding a satellite partner that can meet performance, coverage and regulatory requirements. Commercial negotiations among four large operators could take time even after an agreement in principle.
The partners would need to agree on governance, costs and how to serve markets with different licensing regimes. Projected demand from consumers and public-sector customers may support the business case, but no definitive revenue forecast is established by the initial announcement. Investors should distinguish the strategic intention to explore a service from funded infrastructure construction and actual subscriber income.
Could It Improve Emergency Communications?
Direct-to-phone satellite services have potential value in areas affected by severe storms, natural disasters or temporary damage to cell towers. Where supported, users may be able to send essential messages when traditional coverage is unavailable. Emergency resilience is one of the reasons operators and policymakers are increasingly interested in satellite integration.
Yet coverage is only useful if the service functions on the relevant device, is authorized in the location and has enough capacity. Emergency performance must be tested rather than assumed from promotional demonstrations. Regulators and emergency agencies would also need to establish practical procedures for incorporating satellite connectivity into existing communication systems.
What Does the Initiative Mean for Global Telecom Competition?
Europe’s proposed collaboration fits into a worldwide shift toward hybrid satellite and terrestrial connectivity. Mobile operators, satellite companies and technology vendors are exploring ways to extend coverage using multiple network layers. In the United States, large carriers also have satellite-related projects and partnerships, making competition a global trend rather than a specifically European concern.
If more viable providers enter the market, customers may benefit from stronger coverage and service options. On the other hand, regulatory fragmentation and expensive spectrum or satellite infrastructure could slow rollout. The market is still developing, so forecasts about which company will dominate must be treated cautiously. Announced partnerships should be judged by delivered technology and customer results.
Is There Any Direct Impact on Pakistan or South Asia?
The four-company announcement is principally a European telecom development. It does not establish a new satellite-phone service launch in Pakistan, a local license or a Pakistani commercial partnership. South Asian readers can nevertheless follow it as part of the broader direction of mobile connectivity, which may influence how operators and regulators evaluate satellite coverage in future.
Pakistan and neighboring countries face rural connectivity challenges, making satellite integration a relevant technology topic. However, decisions about spectrum, licensing and availability would be made through their own domestic regulatory processes. A European letter of intent should not be represented as approval for satellite mobile operation in South Asia.
What Happens Next?
The main next steps are any formal spectrum application or bid, a confirmed choice of satellite partner, regulatory decisions and a detailed rollout plan. The operators may also release commercial information about how a service would connect with existing mobile customers. These developments would provide a firmer basis for assessing the project’s viability.
For now, the verified event is a letter of intent and an exploration of future cooperation. No comprehensive network is confirmed as live, and no final launch timetable has been established. Mukhbir will evaluate subsequent official announcements against these milestones rather than treating preliminary cooperation as a completed satellite deployment.
Conclusion
Deutsche Telekom, Orange, Telefónica and Vodafone are considering a joint approach to Europe’s mobile satellite spectrum, positioning themselves for a future direct-to-device connectivity market. The proposal could strengthen rural coverage, network resilience and competition with established satellite players, but it remains at an exploratory stage.
The distinction between ambition and execution matters. Spectrum allocation, an operational satellite partner, ground-network investment and consumer product plans remain to be resolved. The story demonstrates that mobile operators view space-based connectivity as strategically important, while leaving open which technologies and businesses will ultimately succeed.
Frequently Asked Questions
Which telecom companies are exploring the European satellite mobile network?
Deutsche Telekom, Orange, Telefónica and Vodafone signed a letter of intent to explore cooperation.
Have the four companies launched a satellite network?
No. They are considering a joint spectrum bid, not announcing a completed live service.
What is direct-to-device satellite connectivity?
It allows a compatible phone or other consumer device to communicate directly with satellites when the relevant technology and licenses support it.
Why is the 2 GHz band important?
It is part of the spectrum under discussion for mobile satellite services in Europe and requires regulatory allocation and coordination.
Is the initiative a competitor to Starlink?
It is a potential future alternative, but direct commercial competition cannot be assessed until a service is launched.
Will users need a special satellite dish?
Direct-to-device technology aims to connect compatible phones without a separate consumer dish, though capability depends on the service and hardware.
Has a satellite partner been selected?
No definitive partner has been publicly confirmed in the reviewed reports.
Will this service launch in Pakistan?
No Pakistan launch or approval was established by this European announcement.
About The Author